Life Insurance and Estate Plans Must Work Together

What Happened
A Hawaii estate planning firm published a detailed guide examining how life insurance policies and estate plans frequently fall out of alignment as families grow and change over time. The article, written by the Law Office of Keoni Souza in Honolulu, addresses a gap that affects many families: purchasing a life insurance policy during one chapter of life and then allowing it to sit untouched while marriages, divorces, births, business formations, and trust creations reshape the family entirely.
The piece centers on a fundamental misunderstanding many people carry about life insurance. Most assume that a will or trust automatically governs all assets after death. Life insurance operates differently. The insurance company distributes proceeds according to the beneficiary designation on file with the policy, not according to instructions in a will or trust. This means a trust created years after a policy was purchased may have no effect on where those proceeds actually land unless someone takes deliberate steps to coordinate the two documents.
The firm also highlights specific scenarios where misalignment creates real harm: naming a minor child directly as a beneficiary, failing to update a policy after divorce or remarriage, and leaving proceeds to a beneficiary who relies on means-tested government benefits. Each situation carries consequences that careful coordination between the life insurance policy and the broader estate plan can prevent. The article encourages families to pull out their beneficiary confirmation forms and review them alongside their estate planning documents rather than treating insurance and estate planning as separate categories.
What It Means
Life insurance represents one of the most common funding sources families rely on to protect dependents after a death. Yet the beneficiary designation form — a single page that often receives less attention than the policy amount — controls where that money goes. Families who create a revocable living trust and assume the trust automatically captures life insurance proceeds face a significant planning gap. The trust only receives those proceeds if the policy explicitly names the trust as beneficiary, or if proceeds flow into the estate and then into the trust through a pour-over mechanism — a path that typically triggers probate for that portion of the estate.
The issue of naming minor children directly as beneficiaries deserves particular attention. A minor child cannot independently manage a large financial distribution. When no trust or custodial arrangement exists to receive and manage those funds, a court may need to appoint a guardian of the property to oversee the money until the child reaches adulthood. At that point, the child receives the full remaining balance outright, with no structure governing how it gets used. A properly funded trust allows parents to name a trustee, set distribution standards, and specify milestones or age thresholds before a child gains full control. The benefits of coordinating life insurance with an estate plan extend well beyond avoiding probate — they include controlling how and when money reaches the people it was meant to protect.
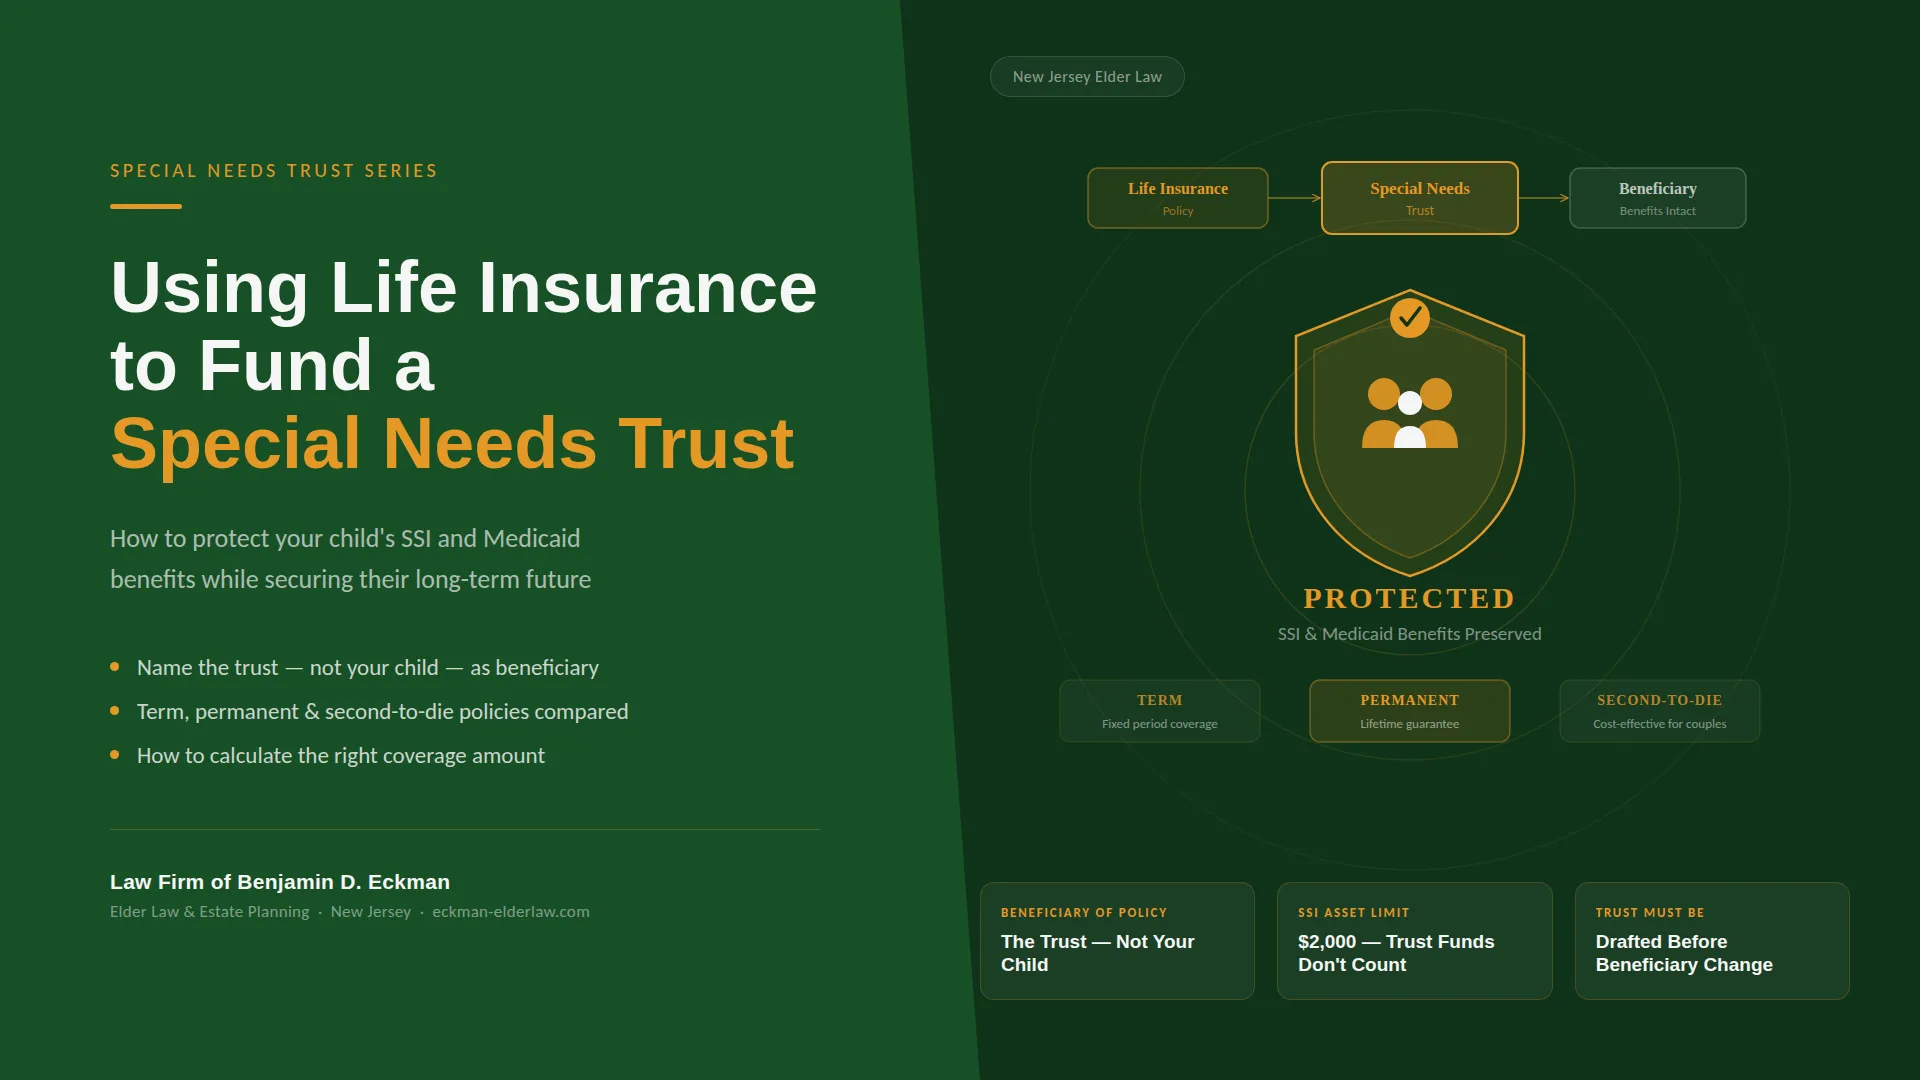
Beneficiaries with special needs represent another critical coordination point. Means-tested government benefit programs evaluate an individual's assets and income when determining eligibility. A life insurance payout delivered directly to a beneficiary who relies on these programs can disqualify that person from benefits they depend on for daily care and housing. Structuring the policy to pay into a properly drafted special needs trust preserves benefit eligibility while still providing supplemental financial support. The same principle applies to beneficiaries facing creditor claims or divorce proceedings. Assets held inside a trust with a spendthrift clause generally remain protected from a beneficiary's creditors until distribution occurs. A direct insurance payout carries no such protection the moment it lands in a beneficiary's hands. Families navigating these scenarios benefit from working with attorneys who specialize in special needs planning to structure both the trust and the beneficiary designation correctly.
Context from SimplyTrust
The coordination challenge between life insurance and estate documents reflects a broader truth about estate planning: the documents work as a system, not as isolated forms. A revocable trust addresses asset distribution, trustee authority, and beneficiary protections. A pour-over will captures assets that fall outside the trust at death. Beneficiary designations on life insurance, retirement accounts, and transfer-on-death accounts determine where a substantial portion of most estates actually flows. When these pieces point in different directions, the estate plan on paper may bear little resemblance to what families actually receive. Understanding how special needs trusts work and how they interact with insurance designations helps families avoid the most common coordination failures.
SimplyTrust helps families document their estate plans, name trustees and beneficiaries, and structure distributions with age-triggered or conditional terms. The platform also provides an estate inventory checklist to help organize financial accounts, insurance policies, and other assets in one place — making it easier to identify where beneficiary designations may need updating. For situations involving special needs beneficiaries, complex family structures, or significant life insurance policies, consulting an estate planning attorney alongside a digital planning tool provides the most complete coverage.
Source: Life Insurance and Estate Planning: Is Your Family Really Protected?