Why a Perfect Estate Plan Can Still Fail

What Happened
A certified elder law attorney in Boise, Idaho recently shared a cautionary account that illustrates one of the most common and costly estate planning failures families face. A longtime client spent years crafting a detailed, carefully considered estate plan. His goals were clear: leave his home, savings, and life insurance to his six grandchildren for their education, and exclude both his long-term companion of 20 years and his three adult children from inheriting anything. The attorney drafted the plan exactly as the client wished.
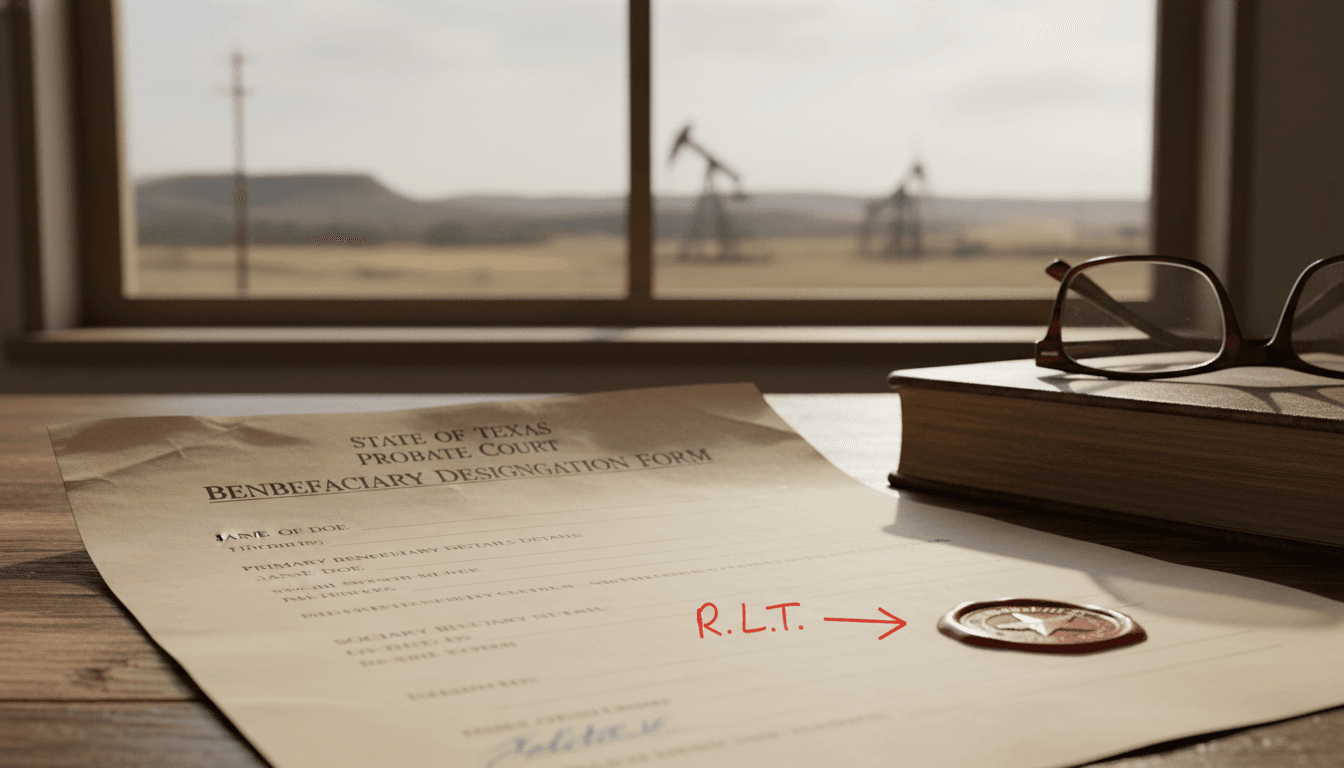
Along with the completed trust documents, the attorney's office sent the client every change-of-beneficiary form he needed to update his life insurance policies, retirement accounts, and bank accounts. Each form asked him to name his trust as the beneficiary on those accounts. The client never returned a single form. The paperwork sat untouched in a corner of his office for five years. When he passed away in 2026, his trust said one thing and his financial accounts said something entirely different.
Because beneficiary designations on life insurance policies, retirement accounts, and payable-on-death bank accounts pass directly to named individuals regardless of what a will or trust instructs, more than half of the client's estate transferred automatically to his companion of 20 years. His six grandchildren received only a modest amount. The estate plan was well-written and the client's wishes were documented clearly. The unsigned forms sitting in that office corner overrode all of it. The attorney published this account in August 2026 as a direct warning to other clients and families.
What It Means
This case exposes a structural gap that affects estate plans across the country, not just in Idaho. Beneficiary designations operate entirely outside of wills and trusts. Life insurance policies, IRAs, 401(k) plans, annuities, and payable-on-death bank accounts all transfer assets directly to whoever is named on the account form at the time of death. Courts consistently uphold these designations over conflicting trust or will language. The trust document holds no authority over an account that names a different beneficiary. This is not a loophole or an edge case. It is how the law works by design.
The practical consequence is that an estate plan functions as a complete system only when every piece aligns. A revocable living trust controls only the assets actually connected to it, whether through direct titling or through a named beneficiary designation pointing to the trust. Any account still naming an individual beneficiary from a prior relationship, a prior plan, or a prior life stage passes outside the trust entirely. Families navigating this reality after a death often discover that the largest financial accounts in an estate, retirement funds and life insurance policies, travel a completely separate legal path from everything the trust was designed to control. Understanding why trust funding matters is essential for anyone who has established a trust and assumes their work is done.
Major life changes create the highest risk of misalignment. Divorce, remarriage, the birth of a grandchild, the death of a named beneficiary, or the creation of a new trust all generate situations where account beneficiary designations need immediate review. Across the country, attorneys and financial planners consistently identify outdated beneficiary designations as one of the most frequent causes of unintended inheritance outcomes. The gap between what a client intended and what actually happened is rarely the result of a poorly drafted document. It is almost always the result of an account form that was never updated. Reviewing your complete asset inventory against current beneficiary designations gives families a clear picture of where those gaps exist.
The Idaho case also highlights the emotional weight of this issue. The client made a deliberate, considered decision to exclude certain people from his estate. That decision was documented, witnessed, and legally sound. The failure was purely administrative. For families in blended situations, second marriages, or estrangements, the stakes of an outdated beneficiary form are especially high. The accounts that bypass trust instructions are often the most valuable ones. Retirement accounts and life insurance policies frequently represent the largest concentrations of wealth in a household, and they move entirely on their own legal track.
Context from SimplyTrust
Estate plans function as interconnected systems. A trust document, a pour-over will, and beneficiary designations across every financial account all need to point in the same direction. SimplyTrust's platform walks users through identifying and organizing assets as part of the planning process, helping families understand which accounts require separate beneficiary designation updates outside of the trust itself. The Glossary of Basic Estate Planning Terms provides accessible definitions for concepts like payable-on-death accounts, trust funding, and beneficiary designations for anyone working through these details for the first time.
For families navigating more complex situations, including blended families, prior relationships, or specific disinheritance goals, understanding the most common estate planning mistakes provides a practical framework for identifying where plans tend to break down. Beneficiary designation misalignment ranks consistently among the most consequential errors, precisely because it produces outcomes that no court can easily reverse after death. The account form, once activated at death, transfers assets immediately and directly. No probate process, no trust administration, and no legal challenge changes that outcome easily or quickly.
Source: Your Estate Plan Can Be Perfect...and Still Fail - Senior Edge Legal